NYC Employees PPO Plan
UNITED HEALTHCARE SERVICES, INC.
- 4.7
- 11.00 Reviews
- 10.00K
- Downloads
- Free
- Price
Screenshots
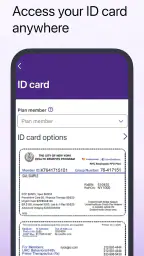
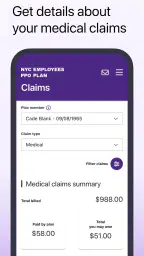
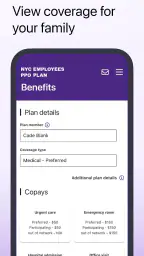
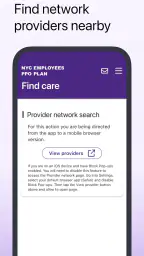
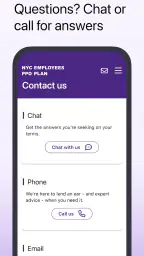
NYC Employees PPO Plan Pros and Cons
Pros
- Clear coverage details for eligible NYC employees and dependents.
- Access to a broad network of participating healthcare providers.
- Useful preventive care and wellness benefits may be included.
- Helps reduce out-of-pocket costs for covered medical services.
- Official plan information can support informed healthcare decisions.
Cons
- Eligibility is limited to qualifying NYC employees and dependents.
- Provider networks and covered services may change over time.
- Some treatments may require referrals or prior authorization.
- Out-of-network care can result in higher personal expenses.
- Plan documents may be complex for first-time members to understand.
 Analysis by All-app
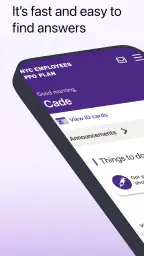
When a health-plan app is used on a shared household phone, the important question is not whether it looks impressive. It is whether the right person can open it quickly, understand what it is for, and avoid mixing one member’s information with another person’s details. That is the lens I used with NYC Employees PPO Plan, a free medical app from UNITED HEALTHCARE SERVICES, INC. It is designed for members of the NYC Employees PPO Plan, and access begins after you receive your member ID card.
My first impression is that this is a focused member-access tool rather than a general health companion. It is not trying to replace a doctor, a pharmacy app, or a broad wellness platform. Its value depends on a specific relationship with the plan: if you are covered by the NYC Employees PPO Plan, it can give you a more direct way to reach plan-related information; if you are not, there is little reason to keep it installed.
How the app fits into a shared household
A realistic use case is a family sharing one tablet or keeping one older phone in a kitchen drawer for household administration. One person may receive the member ID card, while another family member helps with appointments, paperwork, or finding coverage information. In that situation, the app can be useful as a dedicated doorway to the plan instead of making everyone search through email, paper documents, or a general browser session.
The catch is that a shared device changes the privacy equation. A medical-plan app should not be treated like a weather app that anyone can open casually. I would avoid leaving it open on a communal screen, and I would not hand the device to another person without first closing the app and checking what account or member information is visible. The app may be convenient for coordination, but convenience should not become permission to inspect someone else’s health-plan details.
This distinction matters in households where one adult manages practical tasks for another. Helping someone locate plan information is different from taking over their account. I would use the app as a reference point during a conversation, then let the covered member remain the person who decides what information is shared. That approach keeps the household workflow simple without assuming that every family member should have the same access.
For a person who regularly carries the member ID card and handles their own appointments, the app is more naturally a personal utility. For a household organizer, it may still help, but only when the covered member is involved. I would not install it on a child’s device merely because the child is part of the family. The app’s purpose is tied to plan membership, not general family health management.
What I would do before handing over a shared phone
My practical routine would be straightforward. I would install the app on the device used by the covered member, complete access after the member ID card is available, and keep the device protected with its normal screen lock. Before someone else uses the phone, I would close the app rather than relying on the next person to navigate away from it.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I would also keep the member ID card nearby during setup. The store summary makes the starting point clear: access comes after receiving the card. That means downloading the app first is not the same as being ready to use it. If a relative is helping, I would have the cardholder present instead of asking the helper to guess which details belong in the account.
One useful household habit is to separate “finding information” from “making a decision.” A partner might help locate a plan detail, but the member should still confirm what it means before choosing care or relying on it. This is especially important when a quick glance at an app is being used to answer a question that really belongs to a provider, benefits representative, or medical professional.
The app is available for devices running Android version 9 or later, which makes it workable on some older phones but not every aging device. I would check the operating system before planning to use an old household handset. If the phone cannot run it, a browser or the physical member card may be the more practical fallback, depending on what the member needs at that moment.
Setup is member-centered, not a family dashboard
The wording around the app points to a member-access experience, and that shapes how I would organize it at home. I would not expect it to function as a shared family dashboard where several people can freely switch between profiles. Each person should treat their own plan access as their own responsibility, even when a household shares devices or handles errands together.
This is one of the most important boundaries for a spouse, adult child, caregiver, or roommate who helps with administration. Assistance can be useful when the member is present, but the helper should not assume that the app is designed to merge accounts or coordinate several covered people in one place. If your household has multiple NYC Employees PPO Plan members, I would keep each person’s card and access details clearly separated rather than relying on memory.
A simple labeling system can prevent avoidable mistakes. Keep each physical card with the correct person’s documents, and avoid saving screenshots or notes in a shared photo gallery unless everyone understands who can see them. This is not a special app feature; it is a sensible way to reduce confusion when a medical app is used on a family device.
I also would not begin by exploring the app in a hurry outside the member’s normal routine. A better first session is when the cardholder has time to read the screens, confirm that the right plan is being accessed, and decide whether the device is personal or shared. That small pause is worthwhile because a medical account is harder to untangle after information has been entered or shown to the wrong person.
Using it to coordinate without overpromising
The strongest household benefit is likely coordination around ordinary administrative tasks. A member may need to check plan-related information while another person is arranging transportation, preparing questions for a provider, or helping an older relative manage paperwork. In those moments, a dedicated plan app is less cumbersome than searching through unrelated messages and documents.
I would still keep the app in its proper lane. It is not a substitute for calling a provider to discuss symptoms, and it should not be the only source used for urgent medical decisions. If someone in the household is ill, the app may help with plan administration, but it does not turn an administrative screen into medical advice. For anything urgent, the appropriate healthcare service should come first.
Another useful workflow is to prepare before a call or appointment. The member can open the app, review the information relevant to the question, and write down what still needs clarification. A helper can then assist with the list without taking control of the member’s account. This avoids the common problem of opening an app during a stressful conversation and assuming that the first visible answer settles everything.
For couples, I would use a “show, then close” approach: the member opens the relevant screen, shares only what is needed, and closes the app afterward. For adult children helping parents, I would do the same while letting the parent remain the account owner. This is a small distinction, but it makes shared-device use feel cooperative rather than intrusive.
The app’s rating gives me some confidence that other users have found it worthwhile, with a 4.7 average from around 174 ratings and roughly 11 written reviews. I read that as encouraging but not conclusive. A relatively small review conversation cannot tell me how well every household workflow will work, especially when people differ in technical comfort, device age, and expectations about account sharing.
Age, trust, and the person behind the account
The app carries an Everyone age rating, but that label should not be confused with “appropriate for unsupervised access by every person in the home.” A child might be able to open the app from a technical standpoint, yet still have no reason to use an adult’s member account. The relevant question is not only age; it is whether the person is the covered member or has clear permission to help.
This matters particularly when an older adult depends on a family member for digital tasks. I would help with installation and navigation, but I would explain each step rather than silently taking over. The member should know which device is being used, what information is being entered, and when the session is finished. That approach builds trust and makes it easier to spot an incorrect account or mistaken detail.
For teenagers in the household, I would keep the app on the covered adult’s device unless the teenager is independently managing their own plan-related needs. Even then, the account boundary should remain clear. A family’s shared phone can be convenient, but it can also create accidental exposure through notifications, recent-app screens, or an unlocked device. I would treat those ordinary phone behaviors as part of the privacy planning.
There is also a social boundary worth mentioning. A person who helps with insurance paperwork may see sensitive information as part of the job, but that does not mean every household member should see it. The app can support cooperation, yet it cannot decide who should be trusted with a screen. That decision belongs to the member and the people involved in their care.
Where this app is a better choice—and where it is not
Compared with relying only on a physical member ID card, the app is more convenient when you want plan access without searching through a wallet or filing cabinet. Compared with a general browser search, it is more focused because it is tied to the NYC Employees PPO Plan rather than the entire internet. For a covered member who prefers having plan information available on a phone, that focus is the main reason to use it.
On the other hand, someone who rarely uses mobile apps may find the physical card and a direct conversation with the plan easier. A household with strict separation between personal devices may also gain little from installing it on a shared tablet. If your main need is symptom tracking, medication reminders, virtual care, or broad health records, I would look for a tool built specifically for those tasks instead of expecting this app to cover them.
The app is also not the right choice for people outside the NYC Employees PPO Plan. Its usefulness is not general medical access; it is connected to this particular employee plan. That makes the focused design a strength for eligible members and a limitation for everyone else.
The current version is 1.8.0, and the app was released on October 24, 2025. I would keep it updated through the normal app-store process, especially on a shared device, because an older installation can create unnecessary confusion when a member is trying to access plan information quickly. I would also confirm that the phone meets the Android 9 minimum before making it part of a household routine.
My household verdict
I see NYC Employees PPO Plan as a practical, narrowly targeted medical utility. It makes the most sense for an eligible member who has received the member ID card and wants a mobile route to plan access. In a household, it can support helpful cooperation around appointments and paperwork, but only when the member’s account boundaries are respected.
My recommendation is to use it on the covered member’s personal phone when possible. If a shared device is the only option, protect it with a screen lock, keep member materials separated, close the app after each session, and involve the cardholder whenever access or account details are being handled. Those habits do more for a safe household setup than pretending a shared device is automatically private.
It is free, available to Everyone, and has attracted over 10 thousand installs, so it is easy to try if the plan applies to you. Still, I would judge it by fit rather than popularity. The app earns a place on my recommended list for NYC Employees PPO Plan members who want a dedicated plan tool. I would skip it for anyone seeking a complete family health manager, a medical advice service, or a general wellness app.
My bottom line: this is a focused access app, not a household health command center. Used by the right member, on the right device, with clear trust boundaries, it can make everyday plan administration less scattered. Used casually on a shared phone or treated as a substitute for professional medical help, it is the wrong tool for the job.
Frequently Asked Questions
What is the NYC Employees PPO Plan app used for?
The NYC Employees PPO Plan app is designed to help eligible New York City employees and covered dependents manage their health plan information in one place. Depending on the services available through the plan, users may be able to review benefits, access digital identification details, find participating providers, check claims or coverage information, and contact member support without relying entirely on paper documents.
Who can use the NYC Employees PPO Plan app?
Access is generally intended for members enrolled in the NYC Employees PPO Plan, including eligible employees, retirees, and covered dependents when supported by the plan administrator. You will normally need valid member information and an account or registration process to sign in. Availability of specific features can vary according to your eligibility, plan status, employer group, and the services provided in your region.
How do I register or sign in to the NYC Employees PPO Plan app?
After installing the app, users typically sign in with credentials connected to their health plan account or create an account using information printed on their member materials. You may be asked to provide a member ID, date of birth, email address, or other verification details. If registration fails, use the app’s password-recovery option or contact official member services rather than sharing personal information with unofficial websites.
Can I use the app to find doctors and check whether services are covered?
The app may provide tools for searching participating doctors, hospitals, pharmacies, or other healthcare locations, as well as reviewing benefit information. However, provider participation and coverage can change, so search results should not be treated as an absolute guarantee of payment. Before receiving expensive or specialized care, confirm network status, referrals, authorization requirements, deductibles, and estimated out-of-pocket costs with the plan directly.
Is the NYC Employees PPO Plan app free and is my personal information secure?
The app is generally free to download, although normal mobile data charges may apply and healthcare services themselves remain subject to your plan’s terms. Because the app can display sensitive insurance and personal information, install it only from an official app store and verify the publisher. Use a strong password, enable device security, avoid public Wi-Fi for sensitive actions, and keep the app updated.